5 Warning Your Company Needs Immediate Debt Restructuring
Identify the 5 critical warning signs your Singapore company requires urgent debt restructuring to avoid financial crisis.
March 16, 2026 · 0
Table of Contents
Financial distress rarely begins with a single dramatic event.
More often, the warning signs appear gradually: cash reserves shrink, creditors shorten payment terms, statutory payments are delayed, and short-term borrowing becomes necessary just to keep normal operations running.
These signs do not automatically mean a company must enter a formal restructuring process.
But when several appear at the same time, directors should urgently assess whether the company’s debt structure is still sustainable and whether there is a realistic path to recovery.
For Singapore companies, early assessment matters because once creditor enforcement accelerates, the available restructuring options may narrow quickly.
What Do These Warning Signs Actually Mean?
A company can be profitable on paper and still face serious financial pressure if it does not have enough cash to meet obligations when they fall due.
Likewise, one late payment or difficult trading month does not necessarily mean the business is insolvent.
The real concern is persistent deterioration.
Directors should pay particular attention where:
- cash shortfalls keep recurring;
- mandatory CPF or tax payments are being deferred;
- creditors are escalating collection action;
- the business relies heavily on short-term refinancing; or
- suppliers are withdrawing normal trade credit.
These patterns may indicate that the company needs more than ordinary cash-flow management.
They may point to a need for Corporate Restructuring, refinancing, creditor negotiations, operational changes or another formal restructuring route.
Sign 1: Persistent Cash-Flow Shortfalls
A recurring inability to generate enough cash to meet ordinary operating expenses is one of the clearest warning signs of financial distress.
Typical indicators include:
- payroll becoming difficult to meet;
- repeated requests for supplier extensions;
- maxed-out overdrafts or revolving facilities;
- borrowing to cover routine operating expenses;
- overdue CPF or tax obligations;
- persistent negative operating cash flow; and
- debt repayments depending on new borrowing.
The key word is persistent.
A temporary cash-flow shortfall may arise because of seasonal demand, a delayed customer payment or an unusual one-off expense.
That is different from a company that repeatedly enters each month without enough liquidity to meet known obligations.
Why Persistent Cash-Flow Problems Matter
Cash-flow pressure becomes more serious when the business can only continue by:
- increasing borrowing;
- delaying payments;
- stretching suppliers;
- drawing down remaining credit facilities; or
- relying on uncertain future funding.
At that point, the company may be financing today’s obligations by creating tomorrow’s liabilities.
What Directors Should Do
Directors should prepare a realistic short-term cash-flow forecast that includes:
- expected receipts;
- payroll;
- CPF;
- GST and corporate tax;
- rent;
- supplier payments;
- loan repayments; and
- other committed liabilities.
The purpose is not simply to confirm that cash is tight.
It is to identify when the company is expected to run out of liquidity and whether that gap can realistically be addressed.
Sign 2: CPF and Tax Payments Are Being Delayed
Repeated delays in statutory payments are a particularly important warning sign.
A business that cannot pay CPF, GST or corporate income tax on time may effectively be using money owed to statutory authorities as short-term working capital.
That should trigger immediate attention.
Late CPF Contributions
CPF contributions are mandatory employment obligations.
CPF Board currently charges late-payment interest of 1.5% per month, subject to a minimum of S$5, where contributions remain unpaid.
Repeated late CPF contributions may therefore indicate more than an administrative oversight.
They may show that the company no longer has enough cash to meet basic recurring obligations.
Overdue GST
GST-registered businesses generally need to pay GST within one month after the end of the relevant accounting period.
IRAS imposes a 5% late-payment penalty on unpaid GST, with additional penalties potentially applying where the amount remains unpaid.
Repeated overdue GST payments should therefore be treated as a liquidity warning.
Late Corporate Income Tax
Corporate Income Tax that is not paid by the due date is generally subject to a 5% late-payment penalty.
IRAS may also take recovery action.
A company that is consistently delaying Corporate Income Tax payments should assess whether the problem is temporary or part of a broader deterioration in liquidity.
If CPF, GST or tax payments are repeatedly being pushed back to preserve cash for other expenses, treat that as a financial warning rather than a routine timing issue. It may indicate the business no longer has enough liquidity to meet all recurring obligations.
Sign 3: Creditor Pressure Is Escalating
Not all creditor chasing means a company needs restructuring.
Businesses commonly receive reminder emails, overdue notices or payment calls.
The concern is when creditor behaviour begins to escalate.
Warning signs include:
- suppliers shortening payment terms;
- creditors refusing further extensions;
- formal letters of demand;
- lenders declaring breaches;
- secured creditors threatening enforcement;
- repeated collection action; or
- a statutory demand being served.
A Statutory Demand Is a Major Escalation
For compulsory winding-up purposes, Singapore Courts currently state that a company may be deemed unable to pay its debts where:
- it owes a creditor more than S$15,000;
- the creditor serves a written demand; and
- the company fails for three weeks after service to pay, secure or compound the debt.
This is different from saying that a creditor waits 21 days before issuing the demand.
The demand comes first.
The three-week period follows service.
If the company receives a statutory demand, directors should promptly assess:
- whether the debt is genuinely owed;
- whether it is disputed;
- whether payment or security can be provided;
- whether settlement is realistic;
- whether wider creditor negotiations are required; and
- whether formal restructuring protection should be considered.
Ignoring the demand does not make the underlying problem disappear.
Sign 4: Short-Term Debt Is Funding Long-Term Needs
Short-term borrowing is not inherently problematic.
Many healthy businesses use revolving credit, overdrafts and short-term facilities as part of normal working-capital management.
The warning sign appears when short-term borrowing becomes necessary to finance obligations that cannot realistically generate enough cash before the debt falls due.
Examples include:
- continually rolling over short-term facilities;
- refinancing one maturing loan with another;
- using short-term debt to finance long-lived assets without matching cash flows;
- borrowing to cover sustained operating losses;
- depending on future refinancing to repay existing principal; and
- having no realistic plan to reduce total debt.
Why the Maturity Mismatch Matters
If the company owns an asset expected to generate returns over several years but the related borrowing falls due within months, repayment may depend heavily on refinancing.
That creates refinancing risk.
If lenders tighten credit or the company’s financial condition deteriorates, the next refinancing may:
- cost substantially more;
- come with more restrictive terms; or
- not be available at all.
What Directors Should Review
Directors should map:
- debt maturity dates;
- interest payments;
- security granted;
- covenant requirements;
- refinancing assumptions; and
- the timing of expected operating cash flows.
The question is whether the company can repay debt from actual business cash flow or whether it is simply depending on the next lender to keep the structure alive.
Sign 5: Suppliers Are Tightening or Withdrawing Credit
Supplier behaviour can provide an early external signal that confidence in the company is deteriorating.
A supplier changing its commercial terms does not necessarily mean the company is insolvent.
But the pattern becomes significant where key suppliers:
- reduce payment terms from 60 days to 30 days;
- require cash on delivery;
- demand deposits or advance payment;
- suspend deliveries due to overdue invoices;
- refuse to increase credit limits;
- withdraw trade credit entirely; or
- stop supplying the company.
Why This Can Accelerate Financial Distress
Trade credit effectively provides working capital.
If suppliers previously allowed the company 30 or 60 days to pay but suddenly require payment upfront, the company needs more cash immediately just to maintain the same level of operations.
That can create a feedback loop:
- liquidity weakens;
- suppliers tighten terms;
- the company needs more cash upfront;
- liquidity deteriorates further; and
- operations become harder to maintain.
Where critical suppliers stop delivering, the financial problem may quickly become an operational one.
Do These Warning Signs Mean the Company Is Insolvent?
Not necessarily.
A company experiencing one or more warning signs may still have a viable business and a realistic path to recovery.
The distinction is whether the financial problem is temporary and fixable or structural and worsening.
A financially distressed company should assess:
- whether the underlying business remains profitable or capable of becoming profitable;
- whether cash flow can recover within a realistic period;
- whether creditors will support revised terms;
- whether new funding is genuinely available;
- whether non-core assets can be sold;
- whether operational costs can be reduced;
- whether debt can be refinanced; and
- whether continued trading is likely to improve or worsen creditor outcomes.
ACRA recognises that where a company cannot repay its debts, several outcomes may be possible, including restructuring, receivership, judicial management and winding up.
What Should Directors Do Next?
The five warning signs should trigger an urgent financial review, not an automatic assumption that one particular restructuring process is required.
1. Build a Reliable Cash-Flow Forecast
Directors need visibility over expected cash receipts and liabilities.
A short-term forecast can help identify:
- when cash runs out;
- which obligations cannot be met;
- whether funding gaps are temporary;
- which payments are critical to operations; and
- how much restructuring support is actually required.
2. Map the Creditor Position
Identify:
- secured lenders;
- unsecured lenders;
- trade creditors;
- landlords;
- employees;
- CPF obligations;
- tax liabilities;
- related-party debts; and
- creditors already taking enforcement action.
A restructuring involving one cooperative lender is very different from one involving many creditors with conflicting interests.
3. Test Whether the Business Is Still Viable
Restructuring debt is useful only if there is a business worth preserving.
Directors should assess whether the company can generate sustainable operating cash flow after the restructuring.
If the business remains fundamentally loss-making with no realistic turnaround plan, simply extending repayment dates may postpone rather than solve the problem.
4. Engage Key Creditors Early
Where restructuring remains viable, early communication may provide more room to negotiate.
Potential discussions might cover:
- payment extensions;
- revised repayment schedules;
- temporary covenant relief;
- refinancing;
- standstill arrangements; or
- a broader restructuring proposal.
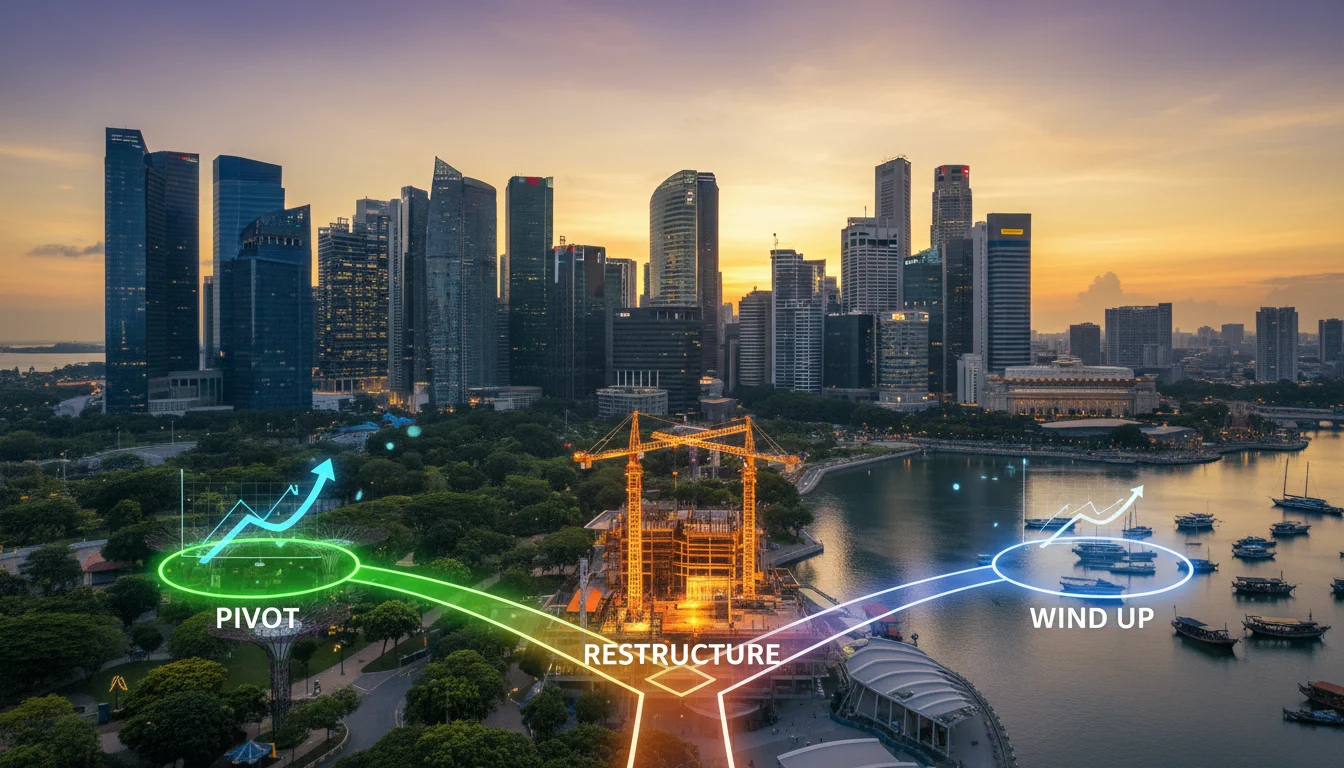
Restructuring Options Available in Singapore
Informal Creditor Negotiations
Where only a small number of creditors are involved, the company may negotiate revised payment terms directly.
This can include:
- extended maturity dates;
- repayment instalments;
- temporary interest relief; or
- revised covenants.
However, an informal agreement generally cannot bind creditors who do not agree to it.
Refinancing
A company may be able to replace expensive or short-term borrowing with more sustainable financing.
Refinancing only works where lenders remain willing to provide capital and the business can support the new debt.
Operational Restructuring
Debt may be only part of the problem.
Operational restructuring may involve:
- reducing overheads;
- closing loss-making divisions;
- renegotiating major contracts;
- improving working-capital management; or
- changing the company’s operating model.
Asset Sales
Non-core assets may be sold to generate liquidity or reduce debt.
Any disposal should be assessed carefully, particularly where the company is approaching insolvency.
Scheme of Arrangement
A Scheme of Arrangement can provide a court-sanctioned mechanism for compromising or restructuring creditor claims.
It can be useful where the business remains viable but unanimous creditor agreement cannot be achieved.
Judicial Management
Judicial management may be considered where the company is or is likely to become unable to pay its debts and there is a reasonable prospect of rehabilitation or another statutory objective being achieved.
Simplified Debt Restructuring Programme
For qualifying smaller companies, the Simplified Debt Restructuring Programme (SDRP) may also be relevant.
ACRA currently states that companies with annual revenue below S$10 million may use the SDRP, subject to the programme’s requirements, to restructure debts while remaining viable.
Eligibility should be assessed before assuming the programme is available.
When Restructuring May No Longer Be Enough
Debt restructuring is not automatically the best solution.
If:
- the underlying business is no longer viable;
- losses continue despite corrective action;
- creditors will not support a workable proposal;
- funding is unavailable;
- key operations have already collapsed; or
- continued trading is likely to deepen creditor losses,
the board should consider whether an orderly winding up is more appropriate.
Where rescue is no longer realistic, Creditors’ Voluntary Liquidation may be one option for an insolvent company that cannot continue because of its liabilities.
When Should Directors Seek Restructuring Advice?
Directors should consider obtaining professional restructuring advice where:
- cash-flow problems are recurring rather than temporary;
- several creditors are demanding payment simultaneously;
- a statutory demand has been served;
- loan covenants have been breached;
- lenders are unwilling to extend facilities;
- the company lacks a reliable cash-flow forecast;
- suppliers are withdrawing credit;
- statutory payments are falling into arrears;
- repayment depends on uncertain refinancing; or
- management is unsure whether continued trading remains financially sustainable.
The earlier the company understands the scale of the problem, the more time it may have to compare restructuring, refinancing and insolvency options.
Need Help Assessing Your Company’s Debt Position?
Recurring cash shortages, statutory arrears, creditor enforcement, refinancing dependence and supplier credit withdrawal should not be treated as ordinary operating problems. ClearView can help assess the company’s liquidity, debt obligations, creditor exposure and available restructuring options.
Speak With ClearViewFrequently Asked Questions
What are the main warning signs that a Singapore company may need debt restructuring?
Common warning signs include persistent cash-flow shortfalls, delayed CPF or tax payments, escalating creditor pressure, heavy reliance on short-term refinancing and suppliers withdrawing normal credit terms.
These signs do not automatically mean restructuring is required, but several occurring together should trigger an urgent financial review.
Does a cash-flow problem mean the company is insolvent?
Not necessarily.
A temporary liquidity problem may be resolved through improved collections, refinancing, creditor negotiations or operational changes.
The concern becomes more serious where the company repeatedly cannot meet liabilities when they fall due and there is no credible path to improvement.
What happens if a Singapore company receives a statutory demand?
The company should assess the demand immediately.
Where a company owes more than S$15,000 and fails for three weeks after service of a written demand to pay, secure or compound the debt, that can support a presumption that the company is unable to pay its debts for compulsory winding-up purposes.
Can debt restructuring reduce the amount a company owes?
Potentially.
A restructuring may involve extended maturity dates, revised interest, repayment instalments or, in some cases, a compromise of principal.
However, creditors do not automatically have to accept a reduction.
Why are delayed CPF and tax payments a warning sign?
These are recurring statutory obligations.
If the company has started delaying them because cash is needed for other expenses, that can indicate the business no longer has enough liquidity to meet all obligations as they fall due.
Is using short-term debt always a problem?
No.
Short-term financing is common in normal working-capital management.
The warning sign is when repayment repeatedly depends on refinancing, short-term loans are funding long-term losses or assets, or the company has no realistic way to reduce the outstanding balance.
Can a small Singapore company restructure its debts?
Potentially.
Eligible smaller companies may be able to use Singapore’s Simplified Debt Restructuring Programme, subject to the applicable eligibility requirements.
Does restructuring guarantee that the company will survive?
No.
Restructuring can create time and reduce financial pressure, but it only works where the underlying business has a realistic path to viability.
When should a company consider liquidation instead?
Liquidation should be considered where the company cannot continue because of its liabilities and there is no realistic restructuring or rescue strategy.
September 29, 2026
September 29, 2026
September 29, 2026
September 29, 2026