When Should a Singapore Startup Pivot, Restructure, or Wind Up?

March 14, 2026 · 0
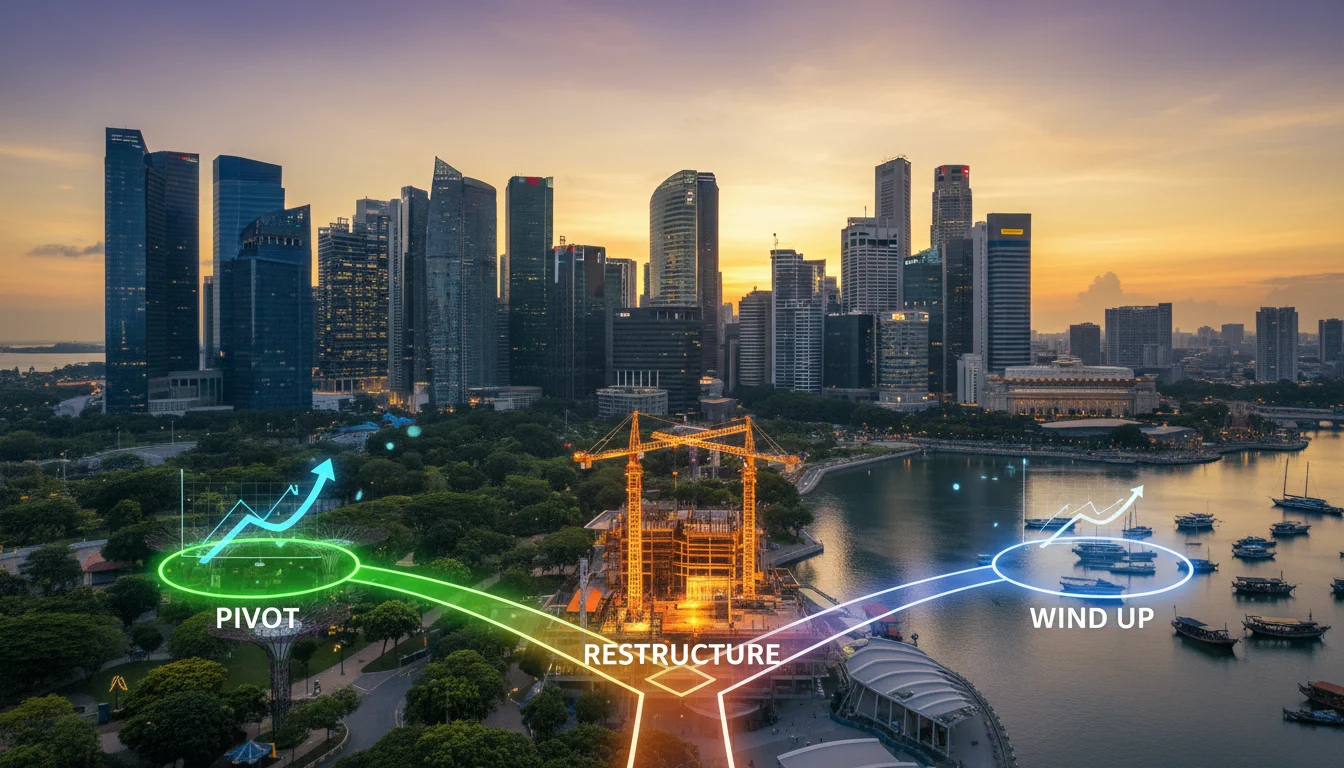
Table of Contents
Running a startup often involves adapting quickly.
A weak quarter, delayed funding round, or short-term cash shortage does not automatically mean the company should shut down. But founders also need to recognise when a business problem has moved beyond normal startup volatility and requires restructuring or an orderly wind-up.
The key is to distinguish between three very different situations:
- the business model still has potential, but needs to pivot;
- the core business remains viable, but the company’s debts or cash flow need to be restructured; or
- there is no credible recovery path and winding up should be considered.
The earlier founders identify which situation they are facing, the more options they usually have.
Start With Financial Health: Liquidity vs. Solvency
Before deciding whether to pivot, restructure, or wind up, founders need a clear view of the company’s financial position.
Liquidity and solvency are related, but they are not the same.
Liquidity
Liquidity refers to the company’s ability to meet short-term obligations as they fall due.
A startup may experience temporary liquidity pressure because of:
- delayed customer payments;
- timing between funding rounds;
- seasonal revenue;
- large upfront operating costs;
- unexpected project delays; or
- rapid growth that consumes working capital.
A temporary cash shortage does not necessarily mean the underlying business has failed.
Solvency
Solvency looks more broadly at whether the company has a credible ability to meet its obligations over time.
Founders should consider:
- current cash reserves;
- expected receipts;
- recurring operating losses;
- outstanding debt;
- employee and CPF obligations;
- tax liabilities;
- contractual commitments;
- contingent liabilities; and
- whether future funding assumptions are realistic.
A company can have valuable assets and still struggle to meet liabilities when they fall due.
Likewise, having cash in the bank today does not necessarily mean the company is financially healthy if substantial obligations are approaching.
Do not base the decision to pivot or continue operating solely on the next expected funding round. Compare the company’s actual runway, creditor obligations and realistic cash inflows against the time and cost needed to execute the turnaround.
Early Warning Signs
Warning signs that financial stress may be becoming structural include:
- repeatedly using high-cost borrowing for payroll;
- declining cash reserves;
- frequent delays in paying suppliers;
- missed CPF or tax payments;
- creditors shortening payment terms;
- continuing losses without a credible turnaround plan; and
- depending on the next funding round simply to meet existing liabilities.
These indicators should be considered together rather than in isolation.
When a Strategic Pivot Is Still Viable
A pivot changes the startup’s product, market, pricing, delivery model, or commercial focus while keeping enough of the underlying business intact to justify continuing.
A pivot makes the most sense where the problem is primarily commercial rather than financial.
Signs a Pivot May Still Be Worth Pursuing
- customers show genuine demand, but not for the current offering;
- the product solves a real problem but targets the wrong segment;
- customer acquisition costs can realistically be improved;
- margins can become sustainable after the change;
- the startup has enough runway to execute the pivot;
- founders have evidence from customers or market data supporting the change; and
- liabilities remain manageable while the new model is tested.
A pivot should be based on evidence, not optimism alone.
Useful evidence may include:
- customer interviews;
- pilot programmes;
- conversion data;
- churn patterns;
- pricing tests;
- sales pipeline quality; and
- unit economics.
When a Pivot Becomes a Delay Tactic
A pivot becomes less credible where founders are making repeated changes without solving the core financial problem.
Warning signs include:
- changing features without improving demand;
- increasing marketing spend without improving economics;
- repeatedly changing target markets without customer evidence;
- depending on future fundraising with no credible investor interest;
- continuing losses with shrinking runway; and
- using new debt mainly to fund an unproven model.
At that point, the company may need more than a commercial pivot.
The issue may be the capital structure, debt burden, or overall viability of the business.
When Restructuring Is the Better Option
Restructuring may be more appropriate where the underlying business remains viable but its current financial structure is not sustainable.
For example, the company may have:
- a viable product;
- recurring customers;
- a credible revenue base;
- valuable intellectual property; or
- a strong pipeline.
But it may still face:
- excessive debt;
- unsustainable repayment schedules;
- creditor pressure;
- short-term liquidity problems; or
- operational costs that need to be reduced.
In this situation, Corporate Restructuring may preserve more value than simply closing the company.
Possible restructuring measures can include:
- renegotiating payment terms;
- extending debt maturities;
- reducing operating costs;
- selling non-core assets;
- raising new capital;
- restructuring shareholder or lender arrangements;
- informal creditor workouts; and
- formal restructuring mechanisms under Singapore law.
Simplified Debt Restructuring Programme (SDRP)
Eligible startups may also consider the Simplified Debt Restructuring Programme (SDRP).
The SDRP is a statutory restructuring framework designed for eligible smaller companies.
Under the current framework, entry into the programme requires more than simply meeting a debt threshold.
The company must satisfy the applicable statutory conditions, and a Restructuring Adviser must assess whether the company is suitable for the programme.
Current eligibility criteria include limits relating to company size and liabilities.
The restructuring process also requires formal notices, creditor information and supporting financial records.
This can include:
- creditor details;
- recent accounts;
- profit and loss information;
- balance sheet information;
- projected cash flow; and
- details of the company’s current and proposed business.
The programme can also provide a statutory moratorium period while the restructuring is being pursued, subject to the applicable requirements.
SDRP therefore should not be treated as simply a cheaper informal workout.
Other Formal Restructuring Options
Scheme of Arrangement
A scheme of arrangement may allow a company to compromise or restructure debts with creditors through a court-sanctioned process.
It can be useful where multiple creditor groups need to be addressed under one restructuring proposal.
Judicial Management
Where a viable startup needs stronger protection while restructuring, judicial management may be considered.
Judicial management may be appropriate where the company is or is likely to become unable to pay its debts, but there remains a reasonable prospect of:
- rehabilitating the company;
- preserving all or part of the business as a going concern; or
- obtaining a better outcome for creditors than immediate winding up.
A judicial manager takes control of the company during the process.
This is a significant step and should be assessed carefully against the company’s commercial prospects and available restructuring alternatives.
Directors Should Focus on Creditor Interests as Financial Distress Deepens
As financial distress becomes more serious, directors need to pay closer attention to creditor interests and the company’s ability to meet its liabilities.
This does not mean directors should simply “keep creditors happy.”
It means decisions should be made carefully and with proper information.
Directors should:
- maintain accurate financial records;
- review cash-flow forecasts regularly;
- understand creditor exposure;
- document major board decisions;
- avoid favouring connected parties improperly;
- question unrealistic funding assumptions; and
- obtain professional advice before creditor losses worsen.
When Winding Up Becomes the Practical Route
Restructuring does not always succeed, and not every startup should continue operating.
If the core business is no longer viable and there is no realistic funding or restructuring path, winding up may become the more appropriate route.
Warning signs may include:
- no credible path to profitability;
- continued deterioration in cash flow;
- liabilities that cannot realistically be serviced;
- key creditors withdrawing support;
- no realistic refinancing or investment options;
- customer demand disappearing;
- restructuring proposals failing; or
- continued trading likely to increase creditor losses.
At that stage, delaying closure may reduce value further.
Voluntary Liquidation vs. Compulsory Winding Up
Members’ Voluntary Liquidation
A Members’ Voluntary Liquidation (MVL) may be appropriate where the startup is solvent and can meet its debts, but the founders or shareholders still want to bring the company to an orderly end.
This may apply where:
- the business is no longer strategically relevant;
- founders want to return remaining capital;
- operations have ceased;
- assets still need to be formally dealt with; or
- a structured solvent closure is preferred.
Creditors’ Voluntary Liquidation
A Creditors’ Voluntary Liquidation (CVL) applies where the company cannot continue because of its liabilities.
In a CVL, a liquidator is appointed to administer the company’s affairs, deal with assets and creditor claims, and bring the business to an orderly conclusion.
Compulsory Winding Up
Compulsory winding up is a Court process.
It may arise where a creditor or another eligible party applies on one of the statutory grounds.
The company does not choose this route voluntarily in the same way as an MVL or CVL.
Pivot, Restructure, or Wind Up: A Practical Decision Framework
Pivot May Be Appropriate Where:
- the core product still solves a real problem;
- customers exist, but the current business model is wrong;
- liabilities remain manageable;
- the startup has enough runway to test the new direction;
- commercial evidence supports the change; and
- the company can execute the pivot without materially worsening creditor losses.
Restructuring May Be Appropriate Where:
- the business itself remains viable;
- debt or liquidity is the main problem;
- creditors may support a workable proposal;
- operational improvements can restore sustainability;
- the company has sufficient time to implement a plan; and
- there is a realistic route back to financial stability.
Winding Up May Be Appropriate Where:
- the business model is no longer viable;
- liabilities cannot realistically be met;
- no credible refinancing or investor solution exists;
- restructuring is unlikely to succeed;
- creditor losses are continuing to increase; and
- there is no realistic path back to sustainable operations.
There is no single financial ratio that automatically decides the answer.
Founders need to consider commercial viability, cash flow, creditor pressure, available funding and legal obligations together.
If Closure Is Becoming Likely
Founders who conclude that winding up may be necessary should also understand the difference between winding up and administrative strike-off.
Why Early Advice Matters
Startups often wait too long because founders hope another customer, investor, grant or funding round will solve the problem.
Sometimes it does.
But relying on an event that is increasingly unlikely can reduce the options available later.
Early restructuring or insolvency advice can help management assess:
- whether the company remains viable;
- how much runway is actually left;
- whether creditors are likely to support a restructuring;
- whether SDRP or another formal mechanism is available;
- whether new funding is realistic;
- whether directors face increasing legal risk; and
- whether an orderly winding up should be considered.
The goal is not automatically to save or close the company.
It is to identify which option preserves the most value and deals with the company’s obligations properly.
Unsure Whether to Pivot, Restructure, or Wind Up?
If your startup is facing recurring cash shortages, creditor pressure or an uncertain funding runway, an early assessment can help clarify whether the business still has a viable recovery path.
Request a Confidential ConsultationFrequently Asked Questions
What is the difference between liquidity and solvency for a startup?
Liquidity refers to the company’s ability to meet short-term obligations as they fall due.
Solvency considers the company’s wider ability to meet its liabilities over time.
A temporary liquidity problem does not necessarily mean the business is no longer viable.
When should a startup pivot?
A pivot may be appropriate where the core business still has genuine commercial potential but the current product, market, pricing or delivery model is not working.
The company should have enough runway to execute the change and evidence showing that the new direction has a realistic chance of success.
When should a startup consider restructuring?
Restructuring may be appropriate where the underlying business remains viable but current debt, cash flow or operating costs are unsustainable.
The aim is to preserve value while creating a more sustainable financial structure.
What is the Simplified Debt Restructuring Programme?
The SDRP is a statutory restructuring framework for eligible smaller companies.
Current entry requirements include statutory eligibility criteria and assessment by a Restructuring Adviser.
The programme can provide a structured process for dealing with creditors and may include a statutory moratorium.
What formal restructuring options are available in Singapore?
Depending on the company’s circumstances, options may include the Simplified Debt Restructuring Programme, a Scheme of Arrangement, and Judicial Management.
The appropriate mechanism depends on the company’s size, financial position, creditor structure and viability.
What is judicial management?
Judicial management is a formal restructuring process where a judicial manager takes control of the company.
It may be considered where the company is or is likely to become unable to pay its debts but there remains a reasonable prospect of rehabilitation or a better outcome for creditors than immediate winding up.
When should a startup wind up?
Winding up should be considered where the company no longer has a credible commercial or financial recovery path.
This may include situations where liabilities cannot realistically be met, funding options have disappeared and continuing to trade would likely increase creditor losses.
What is the difference between MVL and CVL?
An MVL is generally used where the company is solvent and can meet its debts.
A CVL applies where the company cannot continue because of its liabilities.
Both are formal winding-up processes but apply to different financial circumstances.
Is bankruptcy the correct term for a failed startup?
Generally, no.
In Singapore, bankruptcy applies to individuals.
Companies are typically dealt with through restructuring, judicial management, liquidation or other corporate insolvency processes.
Why should founders seek advice early?
Early advice gives founders more time to understand the company’s financial position, communicate with creditors, evaluate funding options and consider formal restructuring tools before the available options narrow.
September 29, 2026
September 29, 2026
September 29, 2026
September 29, 2026